
I once sat with a family who owned a three-million-dollar property in a prime urban neighborhood but were genuinely stressed about a two-thousand-dollar car repair. On paper, they were wealthy, yet their daily lives were governed by a sense of scarcity that didn't match their balance sheet. This is the heart of the liquidity paradox, a growing phenomenon where individuals accumulate significant long-term assets while losing the ability to handle a basic financial hiccup. We have spent decades being told that net worth is the ultimate scorecard, but a high net worth provides very little comfort when you cannot convert it into cash without a thirty-day closing period or a massive tax penalty.
Wealth is often measured by the size of the mountain we build, but financial survival is determined by the flow of the stream at the base. Most people prioritize asset accumulation in forms that are intentionally hard to reach, such as retirement accounts or real estate equity. These instruments are designed to grow over decades, yet our expenses operate on a thirty-day cycle. When too much of your capital is locked in "frozen" assets, you become vulnerable to the unforgiving rhythm of the modern economy. You might have a million dollars in a pension fund, but if you are using high-interest credit cards to pay for groceries, you are effectively paying a premium for the privilege of being wealthy later.
The era of cheap money allowed many people to ignore liquidity because credit was a functional substitute for cash. If an emergency happened, you could simply tap a low-interest line of credit or refinance your home. Recent interest rate hikes have shattered that safety net by making debt an expensive way to solve a temporary cash problem. When the cost of borrowing rises, the distance between your locked-up assets and your liquid needs becomes a dangerous gap. The person who is asset-rich but cash-poor suddenly finds that their "wealth" is a silent observer while their debt servicing costs eat their disposable income.
The traditional goal of owning a home outright is often viewed as the pinnacle of financial common sense. There is an undeniable emotional security in knowing the bank cannot take your roof, but this security often comes at the cost of total illiquinity. I have seen homeowners pour every spare cent into their mortgage, only to find themselves with zero maneuverability when the job market softens or the roof begins to leak. This is the "house-rich, cash-poor" trap where your largest asset is also your least helpful tool during a personal financial crisis.
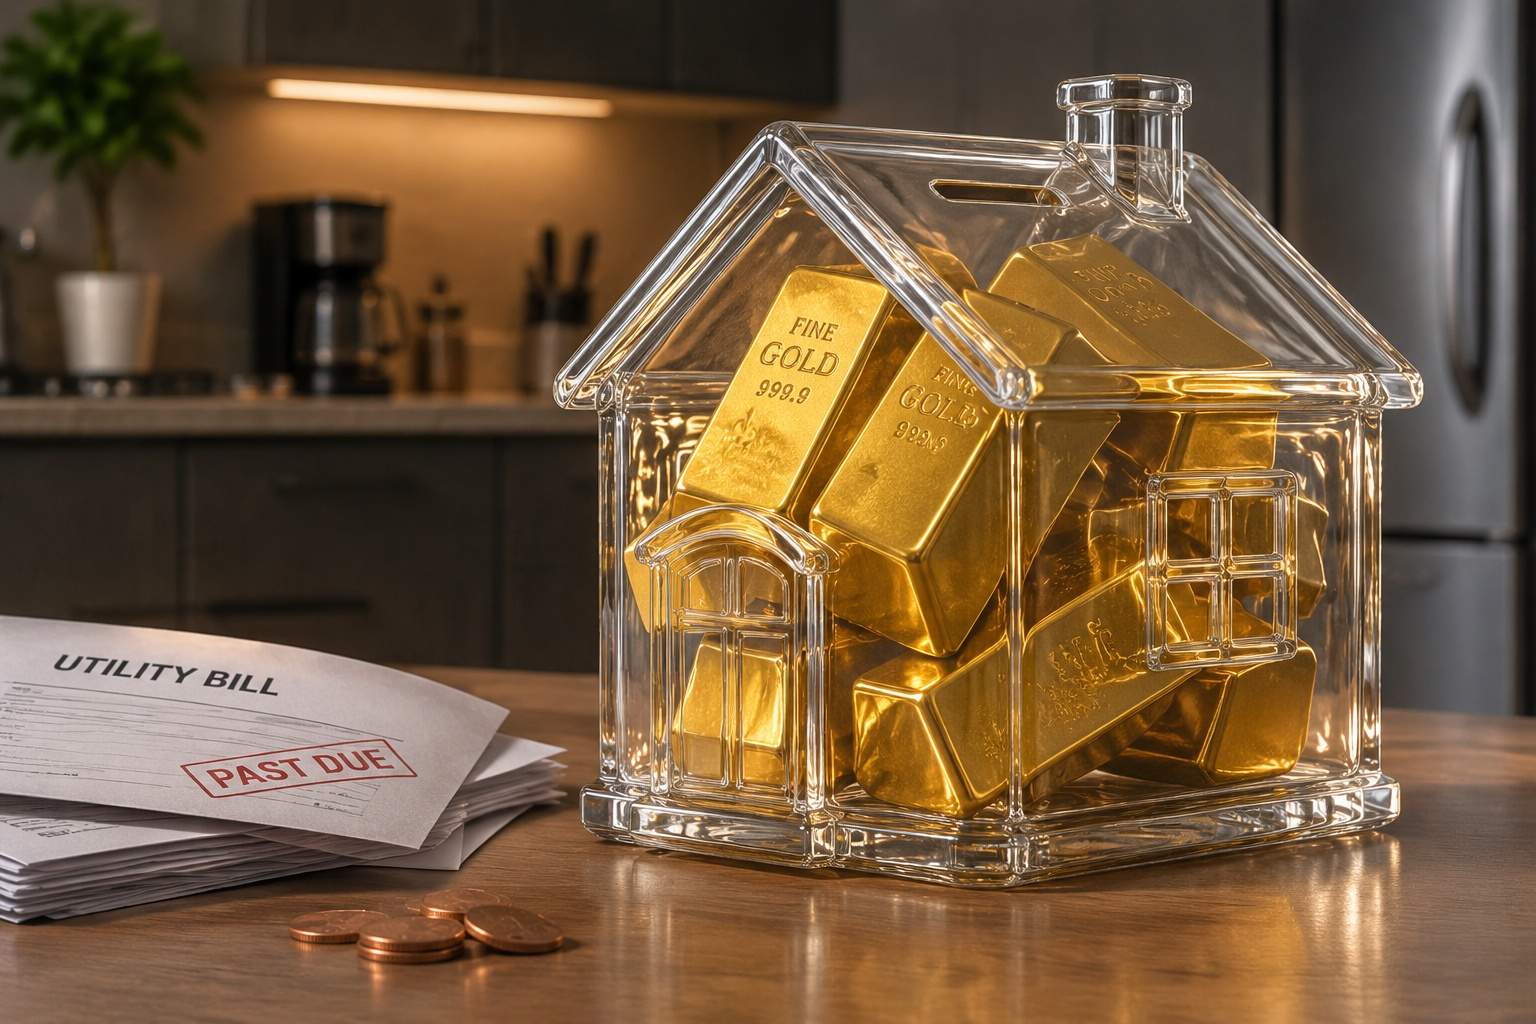
Every dollar you use to pay down a low-interest mortgage is a dollar that is no longer available for an emergency fund or a new opportunity. While reducing debt is generally positive, doing so at the expense of your liquid reserves creates a fragile state of existence. If you need ten thousand dollars tomorrow, having a half-paid-off house does not help you unless you can convince a bank to lend you that money back, which is ironically harder to do when you are actually in a crisis. The opportunity cost of that locked capital isn't just the potential investment return you missed; it is the loss of the ability to act without permission from a lender.
We often treat the emergency fund as "lazy money" because it sits in a savings account earning less than the stock market. This perspective misses the fundamental purpose of liquidity, which is not to generate growth but to provide an insurance policy against forced liquidations. When you don't have enough cash, you are eventually forced to sell your long-term investments at the worst possible time. A market crash is only a disaster if you are forced to sell while the prices are down. Having a robust cash position allows you to leave your retirement accounts alone, effectively protecting your long-term growth by sacrificing a small amount of short-term interest.
There is a real cost to holding cash in an inflationary environment, as the purchasing power of that money slowly erodes. However, we must weigh this predictable loss against the catastrophic risk of being forced to sell stocks or property during a downturn. This is the game of trade-offs that financial practitioners rarely explain clearly. You aren't "losing" money to inflation in a savings account; you are paying a premium for the option to stay invested in your other assets when the world feels like it is falling apart. The goal is to find the point where the cost of holding that cash is lower than the risk of having to liquidate your future to pay for your present.
There is no universal formula for the perfect ratio of liquid cash to long-term assets because every person's tolerance for risk is different. A freelancer with an irregular income needs a much larger liquidity buffer than a tenured professor with a guaranteed salary. The mistake many make is adopting a strategy that worked for someone else without considering their own specific cash flow volatility. We need to stop looking at savings and investments as a competition where one must be better than the other. They are different tools in a toolkit; one is for building the house, and the other is for keeping the lights on while you build it.
The stress of being asset-rich and cash-poor is often invisible to others but devastating to the individual. It creates a state of "wealthy poverty" where you have a high status on paper but live in constant fear of a broken appliance or a medical bill. This psychological burden can lead to poor decision-making, such as taking out predatory short-term loans or neglecting necessary maintenance on the very assets you worked so hard to acquire. True financial health isn't just about the total number at the bottom of the page; it is about the peace of mind that comes from knowing you can handle the unexpected without dismantling your future.
I often wonder if our obsession with the "debt-free" milestone has blinded us to the necessity of financial flexibility. Being debt-free is a wonderful goal, but if it leaves you with a bank balance of zero and no way to respond to a changing world, have you actually achieved security? Perhaps the real measure of success is not how much you own, but how much of your life you actually control when things go wrong.
Disclaimer: Mention of any brand or trademark is for identification purposes only and does not indicate any partnership or endorsement.
