
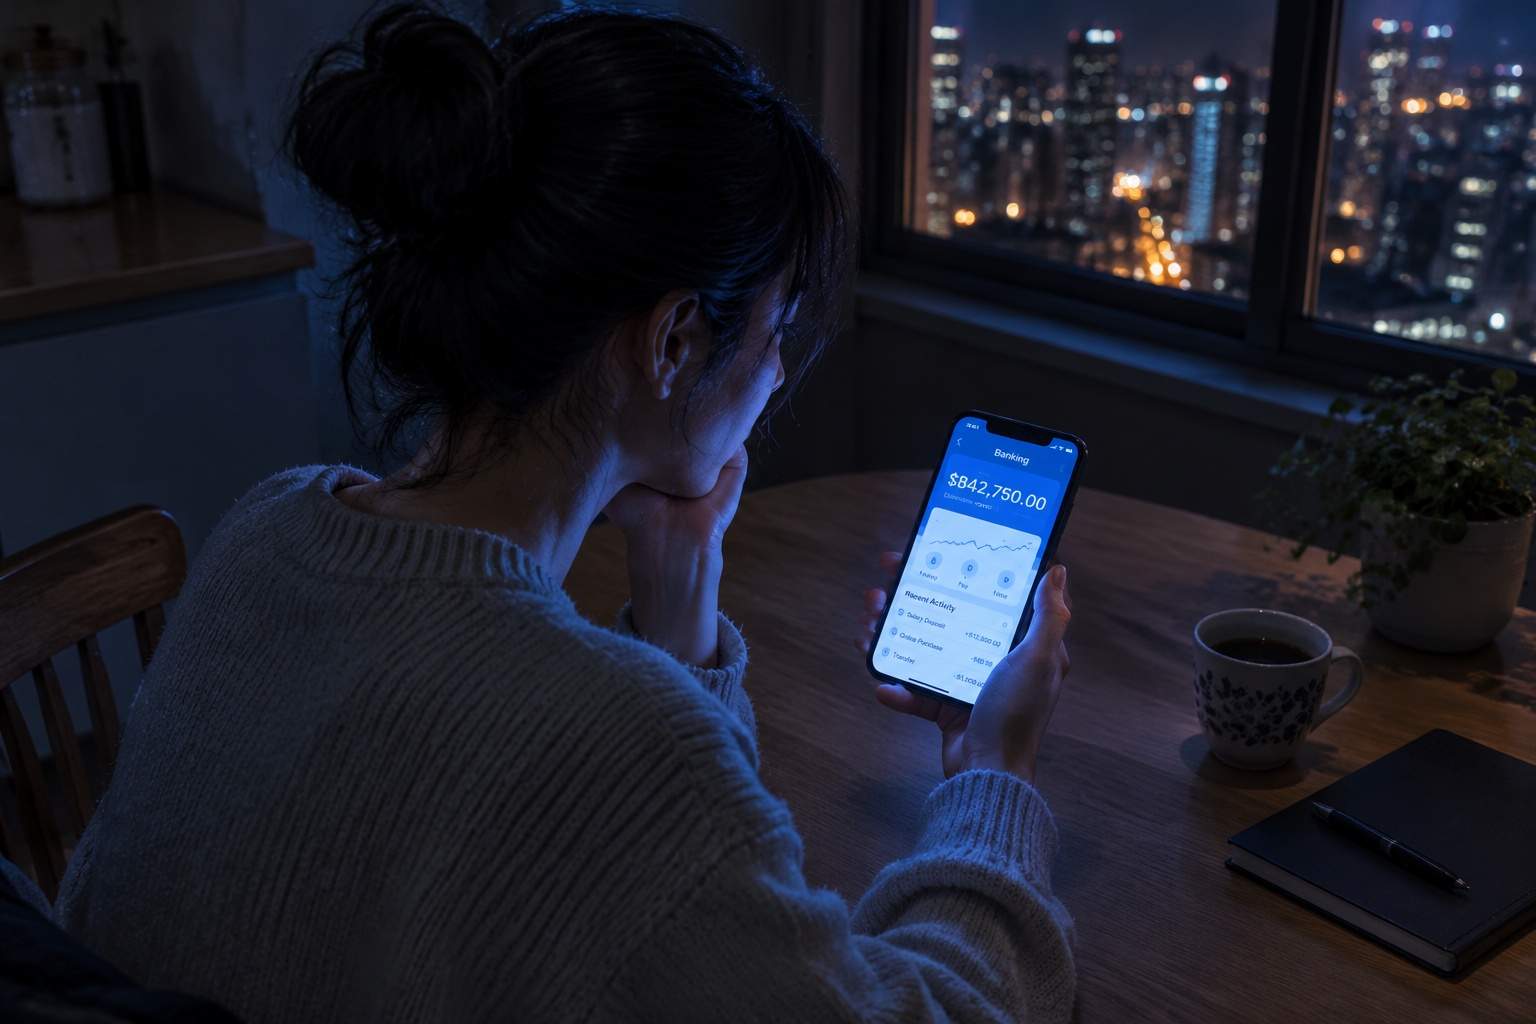
I was standing in my kitchen at two in the morning recently, the blue light of my phone illuminating a banking app that told me exactly what I wanted to hear. The balance was healthy. It was a comfortable, six-month cushion that most financial planners would call a textbook success. Yet, looking at those digits, I felt a strange sense of confinement rather than the liberation I had expected. I realized that the very money I kept for peace of mind was acting as a silent anchor, keeping me tethered to a corporate role that had long since lost its luster. This is the paradox of liquidity that we rarely discuss in polite financial circles. We are taught that cash is safety, but we are rarely warned that too much safety can become a tax on our future selves.
The psychological comfort of high liquidity comes with a hidden price that doesn't show up on a monthly statement. When we talk about an emergency fund, we usually frame it as protection against a sudden job loss or a medical catastrophe. This is a vital function that I would never advise anyone to ignore. However, for many of us, that pile of cash eventually stops being a safety net and starts becoming a psychological barrier to taking the risks necessary for a meaningful career transition. We become so protective of the balance that the idea of spending it on a pivot, a new venture, or a period of unpaid skill-building feels like a failure. We end up trading the volatile but potentially rewarding path of professional growth for the quiet, predictable erosion of our human capital.
Reevaluating the role of a safety net during a personal evolution requires us to look past the interest rate. We often obsess over whether a savings account pays four percent or if a bond fund yields five, but we ignore the return on investment of our own time. If having a year of cash allows you to sleep at night but prevents you from leaving a job that is making you miserable, that cash is technically performing its job while strategically failing you. It is providing a sense of security that is actually a form of stagnation. The risk here isn't that the market will go down; the risk is that your life will stay exactly the same for the next decade because you were too afraid to use your assets as a bridge to something better.
Distinguishing between survival capital and growth capital is the first step toward breaking this paralysis. Survival capital is the money that ensures you don't lose your home if the world turns upside down. Growth capital is the money you intentionally set aside to buy yourself time, education, or a fresh start. When we lump these two together into one giant emergency fund, we tend to treat it all with the same defensive mindset. By separating them, you can acknowledge that while the survival portion should remain untouched, the growth portion is meant to be spent. It is not a loss when that balance goes down if it is being converted into a more valuable asset like a new career path.
The trade-off between market volatility and the certainty of a stagnant career is a calculation we often get wrong. We are wired to fear the ten percent drop in a stock portfolio because it feels like a tangible loss of hard-earned money. We are much less likely to fear the invisible loss of a twenty percent salary increase or the loss of personal fulfillment that comes from staying in the wrong field for five years too long. This is what economists call opportunity cost, but in real life, it feels like a slow-motion weight. Cash is a perfect hedge against market crashes, but it is a terrible hedge against a life spent wondering what else you could have achieved.
Calculating the real cost of a delayed career pivot involves more than just looking at your bank balance. Every year you spend in a role that no longer challenges you is a year you are not building the skills required for the next level of your industry. If you are staying put simply because you are afraid to dip into your liquid savings, you are effectively paying a premium for a safety that you might not actually need. The cost is the difference between who you are now and the person you could become if you had the financial courage to invest in your own transition.
Why a rigid asset allocation can sometimes stifle personal development is a question of how we define risk. Most financial models suggest that as we get older, we should move toward safer, more liquid assets. This makes sense for a portfolio, but it can be disastrous for a career. If you are in your thirties or forties and you have the most human capital potential you will ever have, being too heavily weighted in cash can be a form of self-sabotage. You are essentially betting against your own ability to earn more in the future. Financial independence isn't just about having enough money to stop working; it is about having the flexibility to choose work that matters, even if the path there requires some short-term financial discomfort.
Finding a balance between financial security and the risk of the unknown is not about being reckless with your savings. It is about recognizing that every financial decision is a choice between different types of risk. You can choose the risk of the market, the risk of inflation, or the risk of a wasted career. None of these options are inherently wrong, but they all have different consequences for your long-term well-being. A high-liquidity life might minimize the chance of a short-term crisis, but it often maximizes the certainty of long-term regret.
I'm still not entirely sure what the "perfect" amount of cash is for someone looking to make a big change. I do know that the number I see on my screen at midnight matters less than the person I see in the mirror the next morning. If the money in your bank account is making you feel more like a prisoner than a pioneer, it might be time to ask if you are serving your savings or if your savings are serving you. The most expensive thing you can buy with your emergency fund isn't a new car or a house repair; it's the time and the courage to finally walk through a door you've been standing in front of for years.
Disclaimer: Mention of any brand or trademark is for identification purposes only and does not indicate any partnership or endorsement.
