
Imagine you're in your early thirties, working diligently. You're putting in the hours, developing skills, and striving for that elusive dream of homeownership or a stable family life. But the finish line feels constantly out of reach, a luxury reserved for those with a significant leg up. You see peers whose parents bought their first homes or erased their student loans, while you wrestle with your own educational debt and the relentless climb of the cost of living. This isn't just about individual effort; it’s about the invisible threads of your family's financial past weaving into your present and future.
I’ve watched countless people navigate this financial landscape, and what often gets overlooked is that your journey began long before your first paycheck. It’s the profound internal conflict between believing in self-reliance and the growing realization that systemic factors and inherited circumstances, or the lack thereof, significantly dictate one's financial trajectory. It's the emotional weight of trying to build generational wealth for your own descendants while feeling trapped by the immediate financial pressures inherited from, or exacerbated by, your preceding generations.
It’s easy to look at someone’s financial success and attribute it solely to hard work and smart decisions. And indeed, those are crucial. But I’ve learned to dig deeper. If the path to financial stability is increasingly shaped by an "unseen inheritance"—whether direct capital like a down payment gift or simply a debt-free start to adulthood—how does this challenge our core assumptions about individual merit and the very definition of a "fair" opportunity to build wealth? It's not about blaming anyone, but about recognizing the reality of different starting lines.
Consider two individuals, both equally driven, equally intelligent. One graduates college with no debt, perhaps even a small inheritance, freeing up their early earnings for saving and investing. The other starts with a five-figure student loan burden, perhaps also supporting family members, and faces an immediate struggle to cover basic living expenses. The cost of living today, from housing to groceries, demands a larger slice of income than ever before. For the latter, every earned dollar is meticulously budgeted, often against urgent demands. How do they realistically assess the complex trade-offs between immediate consumption, long-term capital allocation across varying time horizons, liquidity needs, inherent risk tolerances, and the critical opportunity costs involved in trying to shift or sustain a family's financial legacy? The answer, more often than not, is that the long-term vision becomes a luxury they can barely afford to contemplate.
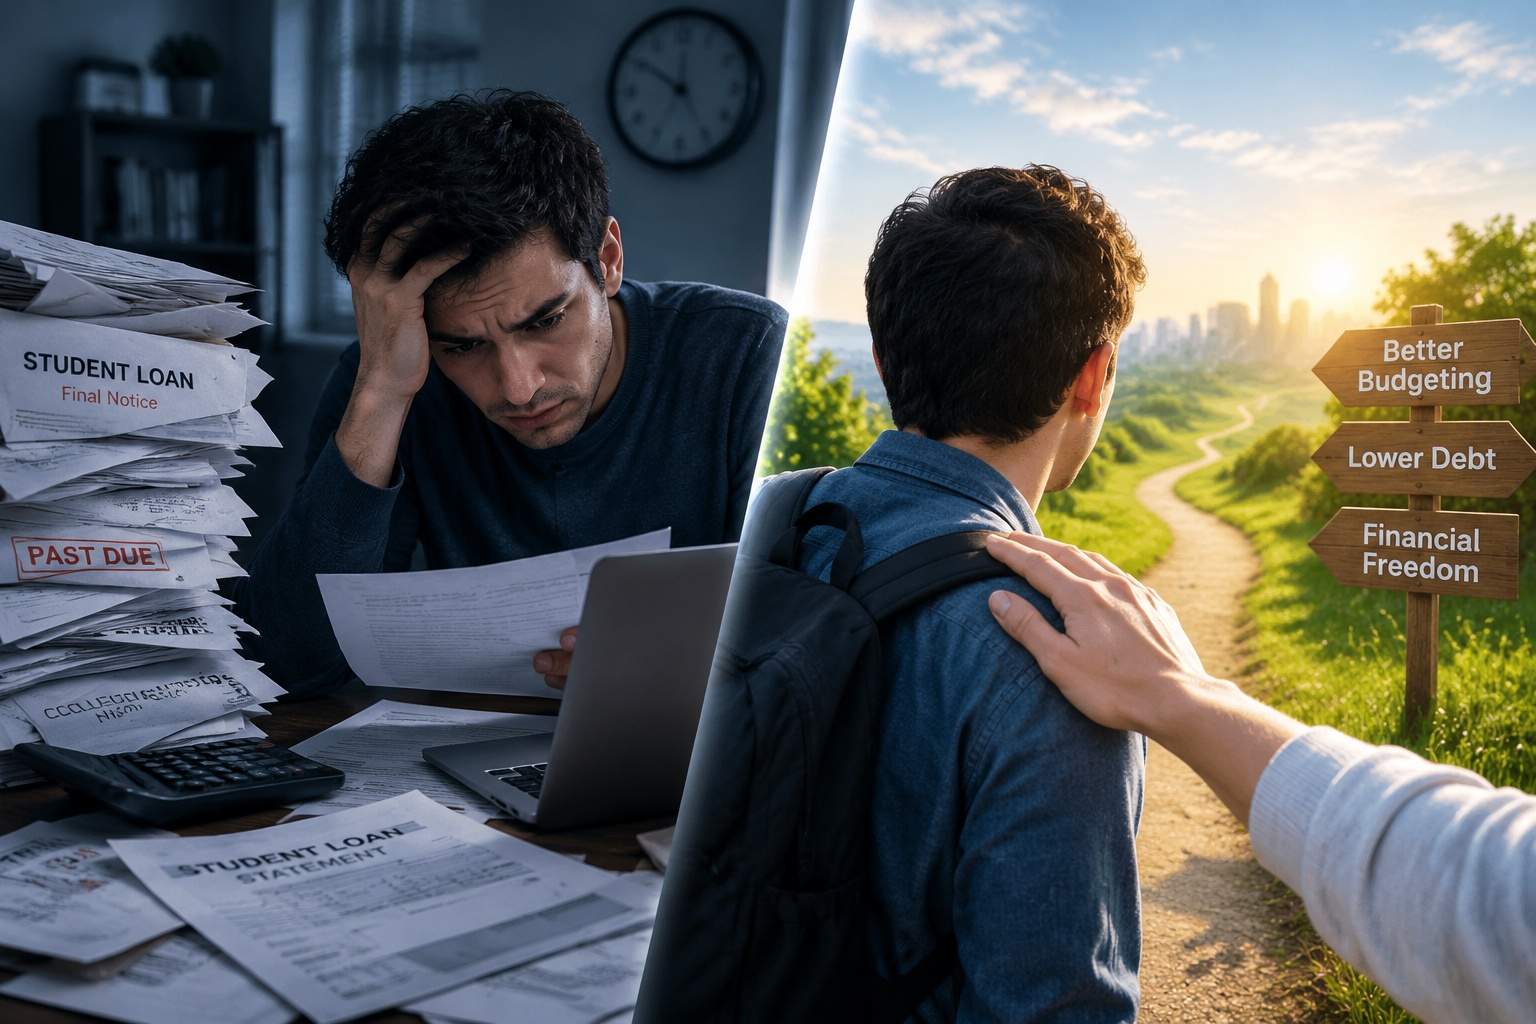
When the daily cost of living feels like a suffocating blanket, talk of long-term financial planning can sound almost cruel. Yet, it's precisely in these constrained circumstances that understanding your options becomes paramount. This isn't a simple equation of "save versus spend" or "invest versus save." It’s about understanding the specific function of each financial tool and how it aligns with your unique position and goals.
Let's be clear: savings are not "outdated" or a "stupid choice." I sometimes hear people dismiss savings accounts as yielding too little interest to matter. But that view misses the point. Savings are your critical emergency fund, your liquidity buffer. They're what protect you when the unexpected happens – a car repair, a medical bill, a job loss. Without readily accessible cash, an emergency can quickly derail years of careful planning, forcing you into high-interest debt that deepens the financial hole. For managing short-term funds, controlling risk, and ensuring security, a well-funded savings account is a non-negotiable component of a robust financial strategy. It’s the foundation that allows you to consider other, riskier ventures.
Once you have that foundation, then we talk about investing. Investing certainly offers the potential for your money to grow beyond what inflation might erode in a savings account. Whether it’s through bonds, funds, or stocks, the goal is to put your capital to work. But it's vital to explain that investing comes with risks. Markets fluctuate. There are no guarantees of steady profits, and you can lose money. The notion that investment automatically "beats" savings or is an easy path to wealth is a dangerous simplification. The discussion around investment should focus on understanding diversification, time horizons, and your personal risk tolerance. For some, allocating a portion of their funds to an investment portfolio might be a crucial step towards long-term wealth building; for others, with pressing short-term needs or a low risk tolerance, it might be an unwise move that creates undue stress. It's about how to choose under different fund uses, not which method is absolutely better.
There’s no universal financial answer, no single product that solves everyone’s problems. That’s what I truly believe. The human element—your unique family history, your current income, your debt load, your time horizon, and your emotional relationship with risk—is always the defining factor. For someone struggling with immediate costs, the "opportunity cost" of not saving for a down payment might feel less pressing than the opportunity cost of not being able to afford a healthy meal tonight.
So, how do you realistically assess your complex trade-offs? You start by understanding your starting line, acknowledging the inherited circumstances that shape your present. You then dissect the functions of different financial instruments. When does putting cash aside in savings make the most sense for your immediate security and liquidity needs? Under what circumstances might investing a portion of your funds, understanding the risks, help you move towards longer-term goals? What other factors, like insurance or debt repayment strategies, will change your final outcome? This isn't about chasing someone else's inherited advantage, but about defining and building your own unique financial horizon. It’s a continuous process of informed choices, balancing today’s demands with tomorrow’s aspirations, and figuring out what kind of legacy you want to build, despite the hand you’ve been dealt.
Disclaimer: Mention of any brand or trademark is for identification purposes only and does not indicate any partnership or endorsement.
