
I've spent years sifting through financial statements and market reports, but the most compelling stories I find aren't always in the numbers. They're in the unspoken anxieties, the delayed dreams, and the choices made by one generation that silently echo through the next. I see it in the eyes of young professionals grappling with relentless inflation, wondering if a first home is a fantasy, or if their student debt will ever truly lift. They look at their parents, perhaps comfortably retired, perhaps struggling with their own later-life finances, and a question hangs in the air: how much of my current financial reality is truly mine, and how much is an inheritance I didn't explicitly ask for?
We often talk about "generational wealth" as if it’s a neatly packaged sum of assets passed down – a trust fund, a deed to a property, or a sizable investment portfolio. That's certainly one powerful form of it, and a fortunate one for those who receive it. But in my experience, the financial legacy we inherit is far more intricate, and often, far less tangible. It's a complex tapestry woven from past decisions, missed opportunities, and sometimes, the sheer weight of economic shifts beyond anyone's control. It’s an invisible hand, guiding – or perhaps pushing – our financial present and future in ways we often don't fully recognize. This isn't about assigning blame; it's about understanding the subtle, yet profound, ways our families' financial histories shape our own.
The traditional definition of generational wealth, focused solely on the transfer of tangible assets, feels increasingly incomplete today. For many, that inheritance isn't just about what's in the bank account, but what's owed from the past, or what could have been if different choices were made decades ago. Think about the student debt crisis, for instance. For some, the ability of parents to contribute to college funds means avoiding crippling loans. For others, a lack of parental resources, or even family financial challenges that required early personal contributions, means starting adulthood with a significant financial anchor. This is a form of generational wealth, or its inverse, playing out in real-time.
Consider two individuals, both starting their careers. One graduates debt-free, perhaps with a small savings account from supportive parents. The other enters the workforce burdened by substantial student debt, perhaps even with the expectation of financially supporting aging parents or younger siblings. While neither received a direct "inheritance" in the traditional sense, their starting lines are vastly different. The first has a wider field of opportunity, able to save for a first home or invest earlier. The second faces an immediate obligation to service debt, delaying those same milestones. It’s not just about inherited money; it’s about inherited financial responsibilities, accumulated opportunities, and even mindsets about money that are passed down through example. This affects everything from our risk tolerance to our very definition of financial stability.
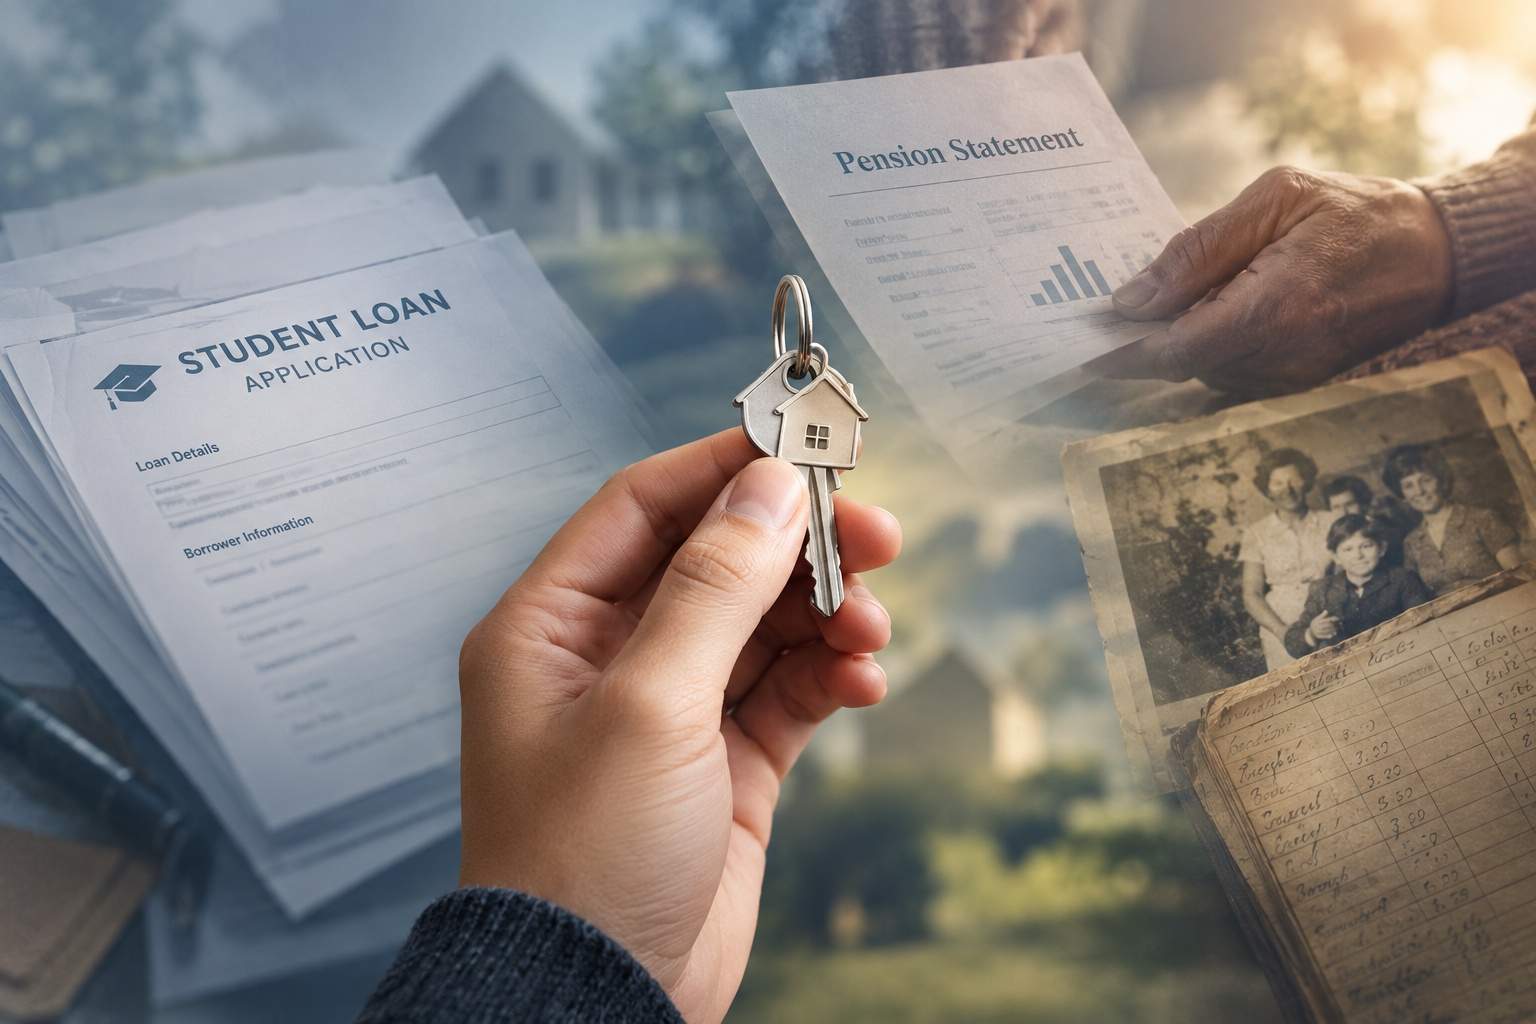
When I speak with clients, particularly those in their 30s and 40s, a recurring theme emerges: the silent anxiety around their parents' retirement planning. It's easy to assume that retirement is a purely individual journey, but the reality is far more interconnected. A parent who planned diligently and built a solid nest egg provides immense peace of mind, freeing their adult children to focus on their own futures. This is an incredible, often unacknowledged, financial gift. Conversely, a parent who struggled, perhaps due to medical issues, market downturns, or insufficient savings, can inadvertently become a financial burden.
This isn't a judgment; life happens. But the consequences for the next generation are tangible. I've seen adult children delay their own retirement savings, postpone starting families, or even put off buying their first home because they're navigating the complexities of elder care or providing direct financial assistance. This financial obligation, while stemming from love and duty, directly impacts their ability to build their own generational wealth. It transforms what might have been a future investment opportunity into an immediate outflow, changing the trajectory of their personal financial journey. So, while you might be diligently saving for your own future, it’s worth asking how your family’s broader financial health might factor into that equation.
Today's soaring cost of living, particularly in urban centers, makes the dream of homeownership seem increasingly distant for many. It's not just about having enough for a down payment; it's about qualifying for a mortgage when incomes haven't kept pace with property values, and when previous generations could often buy homes on a single income. This challenge is magnified by student debt, which wasn't nearly as prevalent or as burdensome for our parents' generation.
I often hear the complaint that "my parents didn't have to deal with this." And while that's not entirely fair – every generation faces its own financial trials – the scale of student debt today is undeniably different. It's an anchor that can hold back individuals from building equity, starting businesses, or even saving effectively. This debt, accumulated often for the purpose of upward mobility, can paradoxically delay financial independence. It represents a significant portion of our "invisible inheritance" – a financial obligation passed on, not directly from parents, but through a societal shift in how education is funded and valued. Understanding this context helps us see that the problem isn't just personal frugality; it's a systemic challenge intertwined with intergenerational financial patterns.
Given this complex backdrop, how do we navigate our own financial choices? It begins with acknowledging that there's no single "right" way, and certainly no magic bullet. When I discuss savings versus investment, for example, I often see people gravitate towards one extreme or the other. Some rigidly cling to savings, fearing market volatility, while others jump headfirst into aggressive investments, convinced it's the only way to "catch up." Neither approach is inherently superior; their utility depends entirely on your specific goals, time horizons, and risk tolerance.
Saving, often dismissed as "lazy money," is a critical foundation. It provides the emergency funds that act as a buffer against life's inevitable surprises – a job loss, an unexpected medical bill. Without this safety net, any small bump in the road can force you into high-interest debt, or compel you to liquidate investments at an inopportune time. So, for short-term goals, or for maintaining liquidity and peace of mind, a well-funded savings account or short-term bond fund is invaluable. It’s not about getting rich, but about staying secure.
Investing, on the other hand, is about harnessing the power of compounding to grow your wealth over the long term. It inherently comes with risks – markets go up, and markets go down. There’s no guarantee of returns, and certainly no "easy profit." But for goals like retirement or a child's education, where you have a decade or more, investing offers the potential for significant growth that simply parking money in a savings account cannot match. The key is understanding that investment is a long game, demanding patience and a willingness to ride out volatility. The choice isn't "save or invest," but "when and how much of each," driven by your unique circumstances and financial goals, always remembering that diversification and understanding risk are paramount.
The financial journey is rarely a solitary one. We are all, to varying degrees, products of our financial pasts, both personal and familial. The question isn't whether we've inherited a financial legacy, but how we choose to acknowledge it, understand its nuances, and ultimately, how we decide to write the next chapter of our own story. What silent ledgers are you inheriting, and what new entries will you make?
Disclaimer: Mention of any brand or trademark is for identification purposes only and does not indicate any partnership or endorsement.
